Ark Insurance Solutions
  • Insurance Plans
    • Employee Benefits
    • Group Health Insurance
    • ICHRA Plans
    • Individual and Family Health Insurance
    • Losing Medicaid or CHIP?
    • Medicare Insurance
    • Dental Insurance
    • Pet Insurance
    • Travel Insurance
  • About
  • FAQs
  • News
  • Request Appointment
  • 801-901-7800
  • Menu Menu
Benefits and Me

Benefits and Me

February 18, 2021/by Rebecca Yates

Benefits and Me

Balancing Caregiving and Your Career

The demands of caregiving and working a part-time or full-time job can leave you exhausted and stressed. When left untreated, chronic stress can develop into serious health problems, including depression, anxiety and cardiovascular disease.

If you are struggling to balance your career with the demands of caregiving, consider the following employer-provided resources:

  • Shift flexibility—Talk to your manager about how to make your schedule less burdensome by altering your hours or telecommuting.
  • Employee assistance program (EAP)—Be sure to discuss your EAP options with your HR representative. They will likely be able to chat about care management and determine if your situation qualifies you for any benefits.
  • Stress management—Talk to your manager and other co-workers about organizing stress-relieving activities at the workplace.

This balancing act between providing care while working full or part-time can be both stressful and exhausting. For additional resources, contact your HR manager.

Lower Your Health Care Costs by Improving Your Well-being

Taking control of your overall well-being can greatly lower your health care costs. Lifestyle changes can help prevent or lessen the severity of health issues, which may result in fewer health expenses and greater well-being.

Consider changes to address components of well-being:

  • Physical well-being—Stay physically active, eat a well-balanced diet to fuel your body, and get enough sleep each night.
  • Mental well-being—Find ways to deal with stress, like journaling or meditating, and consider therapy to talk to a professional.
  • Social well-being—Join a club or sports team to meet new people.

The Basics of FSAs

Flexible spending accounts (FSAs) provide you with a tax advantage to help pay for health care and dependent care. As an employee, you set aside a portion of your pre-tax salary in an account, and that money is deducted from your paycheck throughout the year. Consider the following types of FSAs:

  • Health care reimbursement FSAs can be used for your deductible, copayments, and eligible health care expenses, including prescription drugs, dental costs, eyeglasses, and contacts.
  • Dependent care FSAs let you use pre-tax dollars toward qualified dependent care, such as the cost of nursery schools.

FSAs are beneficial if you have out-of-pocket medical, dental, vision, hearing, or dependent care expenses beyond what your insurance plan covers.

Please reach out to one of our agents if you have questions. 

https://www.ark-ins.com/wp-content/uploads/2021/02/pexels-andrea-piacquadio-3823497-scaled.jpg 1707 2560 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2021-02-18 12:37:392021-02-17 12:38:08Benefits and Me
Free workouts at home

Free Ways to Workout this Year

January 19, 2021/by Rebecca Yates

Free workouts at home

Although we are still in the midst of a global pandemic, and many are working from home or quarantines are keeping you away from the gym, there are several ways you can get that daily workout in for FREE.

Working out is not only good for the body; it is excellent for the mind. We must do our best to keep our spirits up and our bodies healthy during these trying times.

Here are a few ideas:

Walking/Running-it may seem obvious, but walking and/or running just 30 minutes a day can lower your risk for heart disease, burn calories, and elevate your mood. Additional good news, you don’t need any special gear or equipment to do it. A good pair of comfortable shoes will do the trick for walkers and a decent pair of running shoes for runners. Getting outside is literally a breath of fresh air, which we all need, especially mask-free if possible.

Meditation-with so many apps and even podcasts available on meditation, even the novice can practice this mindful technique. In just 10 minutes, you can clear your mind, soothe the soul, and reduce stress. There are also many videos on YouTube for free that you can access on your devices.

YouTube fitness classes– YouTube has an array of videos offering free workouts. From kickboxing to HIIT training and yoga, there really is something for everyone. Subscribe to your favorites and get a new workout each day.


New year, new goals? There has never been a better time to get moving within your own space or in the great outdoors while social distancing.

https://www.ark-ins.com/wp-content/uploads/2021/01/pexels-ketut-subiyanto-4473622-scaled.jpg 2038 2560 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2021-01-19 09:58:132021-01-12 10:24:50Free Ways to Workout this Year

Uninsured COVID-19 Patients, Hospital Bills are Covered

January 7, 2021/by Rebecca Yates

Covid-19 hospital bills


Most major health systems around the country are part of a program through the Center for Medicare and Medicaid Services that provide payments for uninsured patients who have COVID-19.

Medical bills are covered through the pandemic legislation relief, the CARES Act.


Patients may not be informed of this upfront; ask the question if it is a concern.

https://www.ark-ins.com/wp-content/uploads/2017/07/Depositphotos_23825427_l-2015.jpg 1358 1999 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2021-01-07 09:42:212021-01-07 09:42:21Uninsured COVID-19 Patients, Hospital Bills are Covered

Special Enrollment Period (SEP)

December 29, 2020/by Rebecca Yates

If you missed the Open Enrollment period and have had a “life” event, read on.


Did you know that certain life changes may qualify you to enroll in health insurance coverage outside of the standard enrollment period?

Did you or anyone in your household lose qualifying health coverage in the last 60 days? If so, you would qualify for the special enrollment period.

Here are some other examples of qualifying events:

  • Marriage
  • Birth of a child
  • Gained or became a dependent
  • Divorce or legal separation resulting in loss of health insurance
  • Death
  • Change in income
  • Change in zip code/primary place of living
  • Denied Medicaid or CHIP
  • Gained citizenship in the United States
  • Released from incarceration


If any of these apply to you or your family, please give us a call for a quote today!


https://www.ark-ins.com/wp-content/uploads/2017/03/Depositphotos_164827448_l-2015.jpg 1335 2000 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2020-12-29 08:00:522020-12-22 13:01:18Special Enrollment Period (SEP)
Single Mom's Guide to Health Insurance

Open Enrollment Begins November 1–Five Factors to Consider.

October 21, 2020/by Rebecca Yates

Health Insurance


Did you know there are five factors that can affect how much your health plan’s monthly premium is under the health care law?

However, individual states can limit how much these factors come into play.

These five factors are:

  • Age: Premiums can be up to 3 times higher for older people than for younger people.
  • Location: Where you live has a big effect on your premiums. Differences in competition, state and local rules and cost of living are the reasons why.
  • Tobacco use: Insurers can charge tobacco users up to 50% more than those who don’t use tobacco.
  • Individual vs. family enrollment: Insurers can charge more for a plan that also covers a spouse and/or dependents.
  • Plan category: Bronze, Silver, Gold, Platinum, and Catastrophic. The categories are based on how you and the plan share costs. Bronze plans usually have lower monthly premiums and higher out-of-pocket costs when you get care. Platinum plans usually have the highest premiums and lowest out-of-pocket costs.

In addition, insurance companies may offer more benefits, which could also affect costs. Furthermore, insurance companies can not charge women and men different prices for the same plan, nor can they take your current medical history or health into account when otherwise known as pre-existing conditions.


https://www.ark-ins.com/wp-content/uploads/2017/05/life3.jpg 450 660 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2020-10-21 09:00:542020-10-06 10:40:10Open Enrollment Begins November 1–Five Factors to Consider.

Five Insurance Tips for Millennials

September 4, 2020/by Rebecca Yates


Millennials find themselves in the stage of life that may require them to purchase their own insurance. After having aged out of their parent’s insurance coverage and buying or renting a place to live, coverage needs may not be as black and white as one might think.

Knowing these five tips will help navigate through the sometimes-complicated policies out there.

  1. Shop smart for adequate coverage- Although cost is an important factor, having the coverage you need is equally important. You may be tempted to choose the least expensive plan but when it comes time to make a claim, you will see less of a financial benefit. In fact, a high deductible could cause a unexpected financial burden.
  2. Look for discounts- Often insurance carriers will offer discounts for bundling services, such as your home or rental insurance and your car insurance. In addition, there are discounts for being in school and getting good grades. Be sure to ask your agent about these and other possibilities.
  3. Fill in the gaps- An average policy will provide basic coverage but that may not be enough for all your coverage needs. For instance, a rental or homeowner’s policy may not cover personal items such as jewelry over a certain dollar amount.  Be sure to ask if you have collectables or higher value items. 
  4. Purchase life insurance- Life insurance is important, no matter how old you are. For a millennial, it may also save you money on a policy in the long run. It is especially important if you have children. Life insurance can help your family cover unexpected costs in your absence. If you have children, a life insurance policy can support their education or child care expenses.
  5. Consult an independent broker or agent- Talking with an independent insurance agent is the first step in finding the coverage you need and can afford. An independent broker works with multiple providers and can help you navigate the different policies and coverage. They can also help explain some of the terms and conditions that may be difficult to understand.


https://www.ark-ins.com/wp-content/uploads/2018/09/Depositphotos_39307617_l-2015.jpg 1333 2000 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2020-09-04 08:00:222020-08-13 09:33:01Five Insurance Tips for Millennials
Health Insurance Guide For The Self-Employed

Tip 5, The Singles Mom’s Guide to Health Insurance

August 24, 2020/by Rebecca Yates

Beware anything that looks too good to be true!


Yes, your parents were actually right on this one.

Insurance is just math. If it’s cheaper, there is a reason. I have found that most of the time those reasons look like limits on care.

For example, many “cheaper” policies limit cancer coverage to $500,000. Sorry, but many
forms of cancer can eat that up in a month or less. In those types of plans, you would be
left holding the bag on the remaining cost of treatment, or WORSE, having the hospital or
physician refuse to treat you.

If you are looking at insurance options and one is much cheaper than the others, find out
why before you sign up! They often have clauses that lock you in for a year or may not be
qualified coverage so you can’t get in through the marketplace. It may be cheaper because
it excludes something you don’t care about (like maternity when you are done having kids),
but you need to read the fine print. And I mean the 130+ page document that outlines
everything.

Or ask a knowledgeable local agent who has probably read the contract for fun,
like the insurance nerds we often are.


To download the entire guide, click here. 

https://www.ark-ins.com/wp-content/uploads/2019/12/ark-guide-self-employed-angle.png 1890 1500 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2020-08-24 09:24:242020-08-13 09:31:02Tip 5, The Singles Mom’s Guide to Health Insurance
Single Mom's Guide to Health Insurance

Tip 4, Single Mom’s Guide to Health Insurance

July 30, 2020/by Rebecca Yates

Single Mom's Guide to Health Insurance

Know your max liability


So many times, people get hung up on getting a lower deductible and having copays for something to be considered a “good” plan. However, most Americans miss the absolute most important thing in their health insurance documents: The Out-of-Pocket Maximum.

This is the most you would pay in one calendar year if everything went horribly wrong. If
you have health insurance, this is the maximum of liability and it’s a number you need to be
aware of!

For example:

I often have clients tell me they want the “best” plan and are willing to pay for it! They want a
$250 deductible. In my state, the $250 deductible plan has a $7,900 out-of-pocket maximum
and is often 30% higher than an HSA plan for monthly premiums.
However, if they enroll in an HSA they can often get a lower out of pocket maximum. My plan
is a $4,500 deductible, but that is also the out-of-pocket maximum. At 30% less expensive
per month, it’s an absolute bargain! But most people ignore this plan because all the see is
the deductible.

Let’s look at an example:

Johnny needs a $60,000 heart surgery.

Plan 1: He’s paying $500 a month to get the lower deductible. That equates to $6,000 a year
in insurance premiums. When he has his surgery, he will pay $7,900. So, in total he spent
$13,900. Which beats the pants off $60,000 any day! But it’s not the best he could have done.

Plan 2: He is now enrolled in the HSA plan. He is paying $350 a month. That equates to
$4,200 a year in insurance premiums. BUT when he has his surgery, he pays $4,500. That
means he spent $8,700 less than on the “best” plan. But wait! He also got to put that $4,500
through an HSA account and gained the additional tax savings.


Read more here: The Single Mom’s Guide To Health Insurance


https://www.ark-ins.com/wp-content/uploads/2017/05/life3.jpg 450 660 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2020-07-30 13:21:172020-07-28 13:29:41Tip 4, Single Mom’s Guide to Health Insurance

Reflections on Ark Insurance 10 Year Anniversary

April 10, 2020/by Rebecca Yates

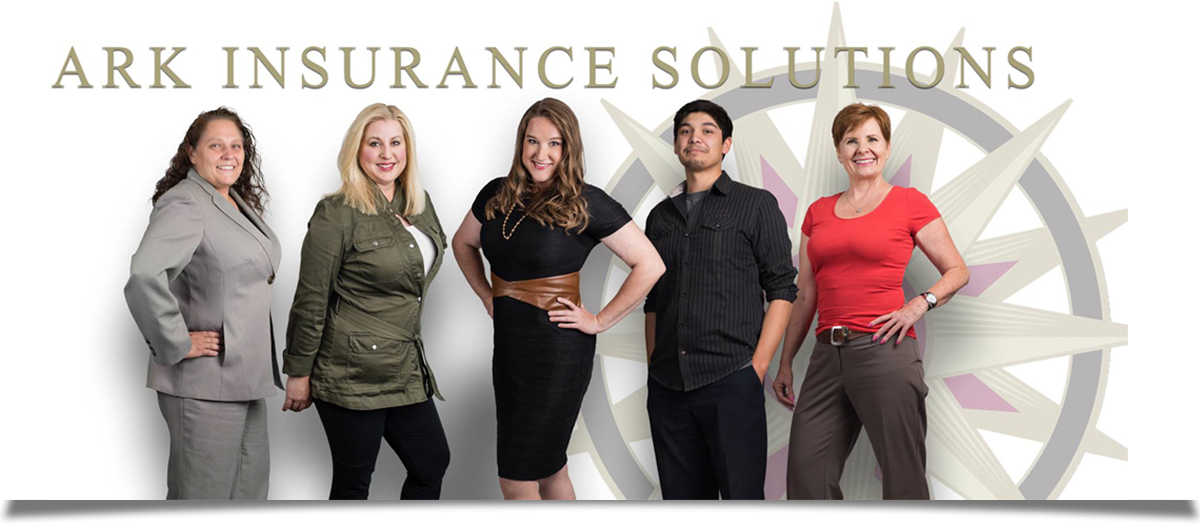
Ark Insurance Solutions Team

I quit my job in the fall of 2009. The next week my daughter and I contracted H1N1. I spent the first actual week of ‘self-employment’ (it was unemployment at that point, let’s be honest!) in quarantine for a pandemic in the middle of the worst recession our country had ever seen. Sound familiar?

I had been working for a large brokerage firm. The company that had pulled me into the insurance industry had sold and lost much of its heart in the transaction. Suddenly I was being told only to help clients that could justify the cost. I knew that if I was going to stay in this industry, an industry that I had grown to love (and be pretty nerdy about), I had to leave. For me, it was never about the dollars, it was always about taking care of my people. As a single parent, the idea of leaving a stable job with a steady paycheck was terrifying, but I had become miserable in the year that the new company had taken over and had to go.

Then the most amazing thing happened. My clients, in a show of loyalty that still brings me to tears, stuck with me. They encouraged me. They fought with me and listened to me cry. They pushed me to make sure I read and understood all the new laws going into place at the time (Obamacare or Affordable Care Act). They helped me stand strong and grow. By the time I was ready to file my corporate documents on April 10, 2010, I had enough revenue to sustain myself and my daughter, and even more, amazing, Ark was already growing.

Soon I realized that I couldn’t do this alone, and in one of the scarier steps in my life, I decided to make my first hire. In February 2011, I posted on Facebook that I needed some help. I believe he posts included something to the effect of I need an intern. Or a college kid who is willing to work on the cheap. Even if it’s only a few hours a week! I’m in desperate need but can’t pay much.Enter one of my former clients. She messaged me and asked why I hadn’t reached out to her. My honest answer was, “I know how much you make, and I can’t afford you.” We still laugh about this. She let me know that the ability to work from home was more important to her than the money and agreed to work with me until we found a budget that fit for us both.

I knew I had gotten lucky but had NO idea HOW lucky I had gotten in that hire. When we lost our biggest client due to an acquisition, BOTH of us cut our pay to make it through. She was unafraid to tell me the truth, willing to suffer with me, and give all she had to make sure our clients, and I, were supported. I can honestly say this company would never have survived if MaryAnn hadn’t joined it when she did. Fast forward after a few expensive learning moments, times when the cash got so tight I was surfing for change in the couch to make payroll, and growing our team to 10+ folks and here we are today. We have won international awards, been given genuinely amazing opportunities to participate in conversations at a federal level that deeply impacted the lives of Americans, and have done it all growing closer as a work family.

We have a team of amazing humans. Our entire company culture has been built on the same principles that brought MaryAnn into the fold: Always do what’s right for the client first, and be supportive and flexible with our team. All of us work different hours and in different locations according to what we need in our lives. Because in the end, our business is here to support and make lives better, both ours and those of our clients.

We’ve built lasting relationships with our clients, and they have given us the most amazing gifts in the form of referrals. We’ve never done extensive marketing. We’ve never had to push or buy leads. We’ve never even been in a place where we were worried about an empty pipeline. We’ve seen massive changes in our industry. We’ve had massive cuts in pay, changes in how we are regulated, shifts in every aspect of how we do business, and through it all our clients have stood by us and helped us grow. Our clients have become our friends. An extension of our work family that we care for like we would make our favorite aunt. We fight for them, cry with them, and celebrate when they have a new baby or get a new job. Serving our clients is an honor, and we are all so grateful that they allow us to be a part of their journeys.

We were supposed to be having a party for the Ark team. We were going to have lunch and then go axe throwing. With social distancing, we have had to postpone our celebration. But the opportunity look back and see where we have come since the last pandemic and economic crisis is one that shouldn’t be passed up. Things feel scary and uncertain. They did before too. What it tells me is while the moment feels bleak, the people are showing up for each other, just like they did in the recession.That even though we are all afraid, we are pushing through, and when we work together, we will come out together, better than before. I’m looking forward to seeing where the next 10 years will take us!

https://www.ark-ins.com/wp-content/uploads/2020/04/Rebecca-by-Emily-London-Portraits-www.emil-030-No-Logo-Web-Version.jpg 1400 2013 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2020-04-10 08:00:072020-04-14 08:46:11Reflections on Ark Insurance 10 Year Anniversary
Don't lose your health insurance.

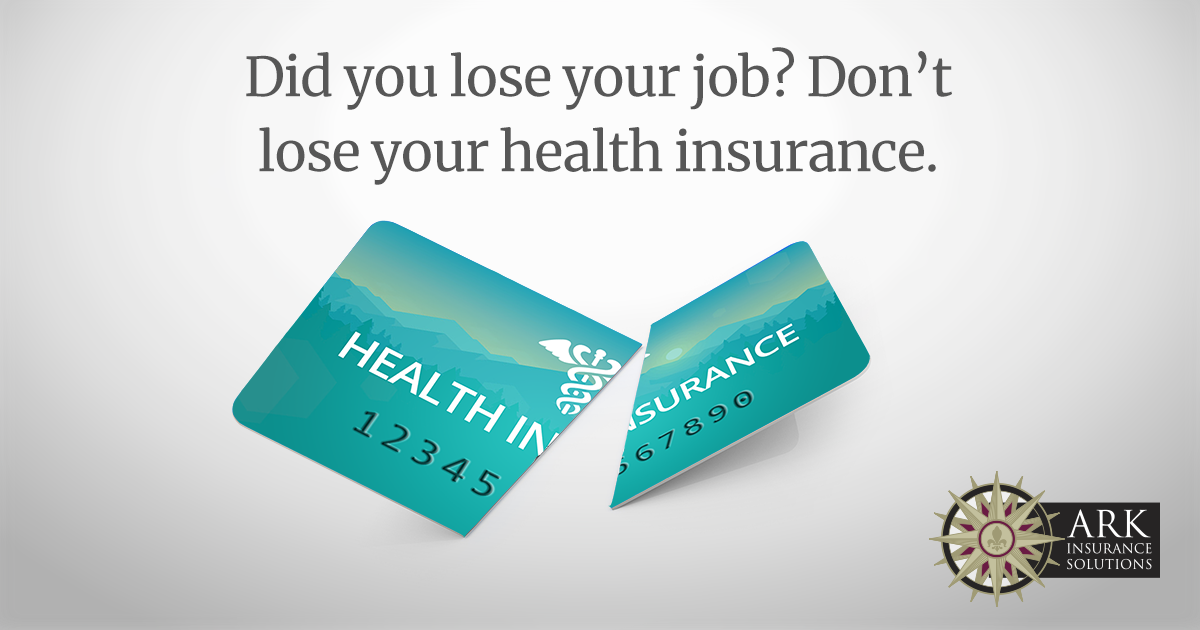
Did you lose your job? Don’t lose your health insurance.

April 7, 2020/by Rebecca Yates

Don't lose your health insurance.

If you lose your job you need to act fast to get the insurance figured out.

There are multiple options for people who have recently lost insurance, but you only have 60 days to enroll through the federal exchange.

COBRA may not be the only option and you may even qualify for Medicaid.

Let us help you navigate the options.

If you’ve recently lost your health insurance (or are in danger of losing your insurance) due to a layoff or job loss, we can help.

Please give us a call or complete the form below and we’ll get back to you within 4 hours (Mon.-Fri. 9am-5pm) for a phone consultation.

https://www.ark-ins.com/wp-content/uploads/2020/04/Ark-dont-lost-health-ins.png 630 1200 Rebecca Yates /wp-content/uploads/2019/10/ark-logo@2x.png Rebecca Yates2020-04-07 11:12:282020-05-22 11:59:12Did you lose your job? Don’t lose your health insurance.
Page 5 of 9«‹34567›»

About Us


In 2010, Rebecca Yates launched Ark Insurance Solutions, LLC based on her desire to focus not solely on the dollar, but to put individuals and clients first. It is this founding principle that has helped make Ark Insurance Solutions LLC the most trusted resource for affordable health insurance in the greater Salt Lake City, Utah area. Read More>

Recent Posts

  • Health Insurance Open Enrollment: What’s New This Year, and What to Expect
  • ICHRA Name Changed To CHOICE Arrangement
  • Evaluating Health Insurance Broker Bids: A Guide For Getting Through The Process
  • Medicare’s New GLP-1 Weight Loss Pilot Program
  • What’s the Buzz? Could an ICHRA or QSEHRA Plan Be Right for You?

Call a Licensed Insurance Agent: (801) 901-7800 TTY: 711

By calling this number, you will be directed to a Licensed Insurance Agent.

Hours of Operation: Monday – Friday, 9:00 AM – 5:00 PM MT

TPMO Disclaimer: We do not offer every plan available in your area. Currently we represent 8 organizations which offer 45 products in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options.

Not affiliated with or endorsed by the government or the federal Medicare program.

Ark Insurance Solutions is a licensed and certified representative of Medicare Advantage organizations and stand-alone prescription drug plans. Each organization has a Medicare contract. Enrollment depends on contract renewal.

Connect With Us On Social Media

FacebookYouTubeInstagramThreadsLinked In

Ark Insurance Solutions
655 East 4500 South, Ste 210
Salt Lake City, UT 84107

Phone: 801-901-7800
Fax: 801-305-4947
Email: info@ark-ins.com

ARK Insurance Solutions LLC - Copyright © 2017-2026. All Rights Reserved.
  • About Us
  • Frequently Asked Questions (FAQs)
  • News
  • Privacy Policy
  • HIPAA Notice
  • Terms & Conditions
  • Request a Quote
Scroll to top Scroll to top Scroll to top